SB 258 & Municipal Incorporations
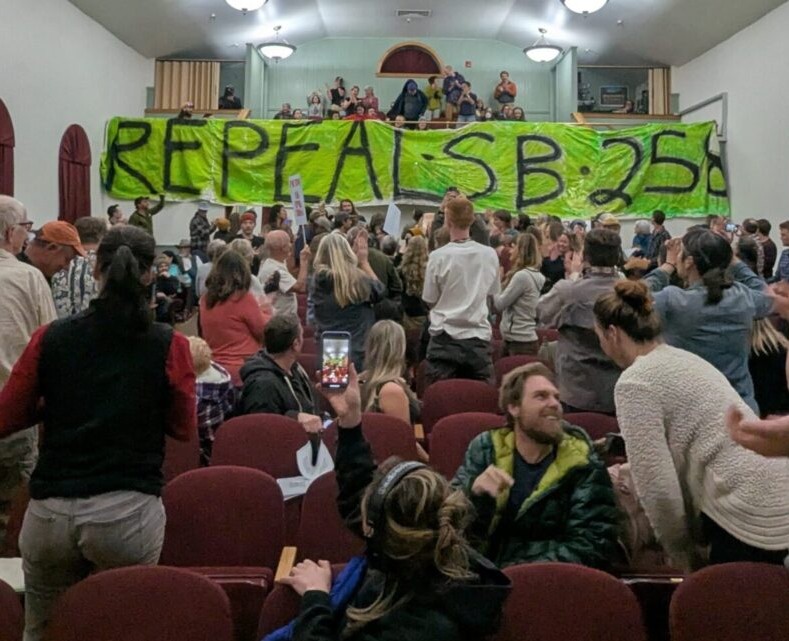 SB 258 and the Municipal Incorporation Saga.
The SB 258 Incorporation bill has been a thorn in the sides of many Utah counties, since 2024. Wasatch, Grand, Summit and Kane Counties have already been directly affected. Great KZMU Report of legislative origins of SB 258
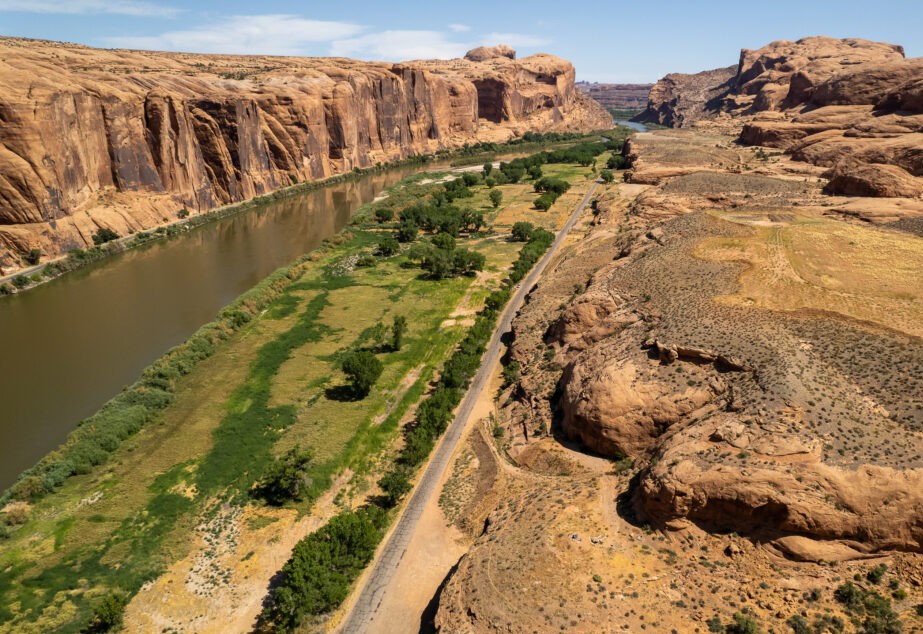
Kane Creek Development Watch & Living Rivers Council in Moab (Grand County) filed a lawsuit, in February 2026, against the Lt Governor’s office claiming SB 258 is unconstitutional. KPCW Moab Lawsuit Report MOAB Sun News Report Fox13 News Report on original Kane Creek Development.
Wasatch County has declared their support of the Kane Creek Lawsuit in October 2026. With their Wasatch Highlands and Wallsburg developments interested in the municipal incorporation process, Wasatch County is feeling pressure from state overreach, too. Summit County also wants legislature to repeal SB 258.
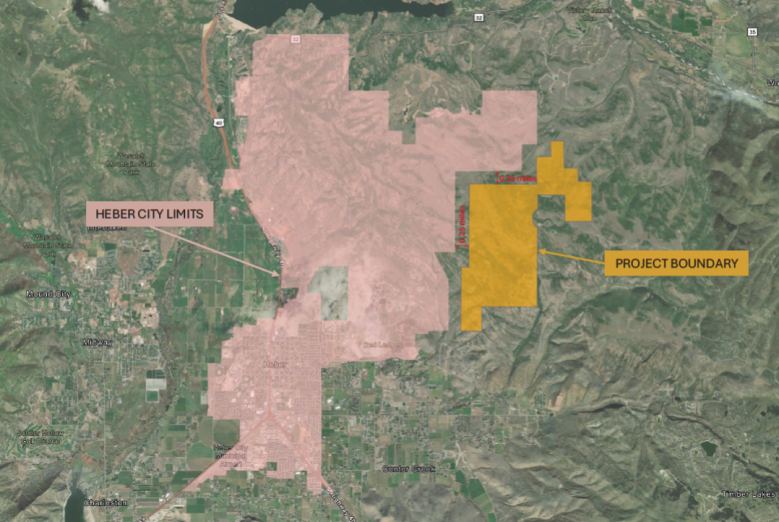
10-28-2026 In Wasatch County, Wasatch Highlands Incorporation- The public hearing was October 27, 2026 at the Wasatch High School Auditorium at 6pm. The Philo Development’s request for a legislative development agreement that would have allowed about 144 residential lots on approximately 740 acres of state trust land (SITLA) above Heber City was denied by Wasatch County, so they applied for a Municipal Incorporation. Wasatch Highlands’ Feasibility Study Wasatch County’s Response to Feasibility Study
Park Record Report entitled, “Wasatch Highlands: The new town Wasatch County didn’t ask for.”
**Go to our WTPA YouTube Page to hear portions of the public hearing! We apologize for the poor quality of the video. We did not anticipate that we were going to record, but quickly reacted when it was clear no one was recording the hearing.
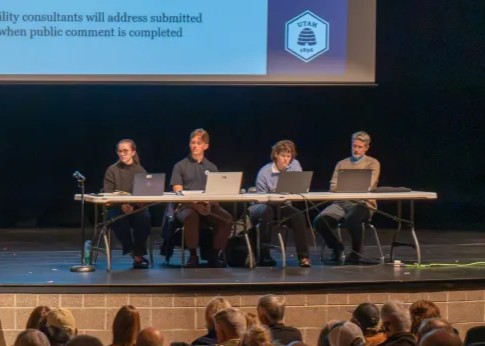 During the public hearing there were many indications that the Lt Governor’s Office did NOT take this process seriously. First, they sent 3 young interns from the Lt Governor’s office (see picture), who couldn’t have been more than 25 years old. No mid-level government office representatives, at all. Second, the meeting was not being recorded by the Lt Governor’s office or Wasatch County Council, so no state requirement to record this meeting, to show it even happened? Park Record Article KPCW Report
Steve Waldrip, from the Governor’s Office, threatened Wasatch County first, long before this public hearing. Wasatch County had informally denied the development application by the developer in an August 12, 2026 meeting. Councilmembers stated they were not interested in the density proposed (one home per 5 acres), which conflicted with standard zoning that limits the area to one unit per 160 acres. KPCW Report Utah News Dispatch Report
It was assumed that the developer must have gone back to the state to complain, because at the following HEBER CITY MEETING, (go to 1:56:40 into recording, to hear full discussion) Steve Waldrip shows up and tells Heber Council to give Wasatch County a message. Waldrip threthened Wasatch County’s road funding, and any other state funding. What?! KUTV Report KPCW Report
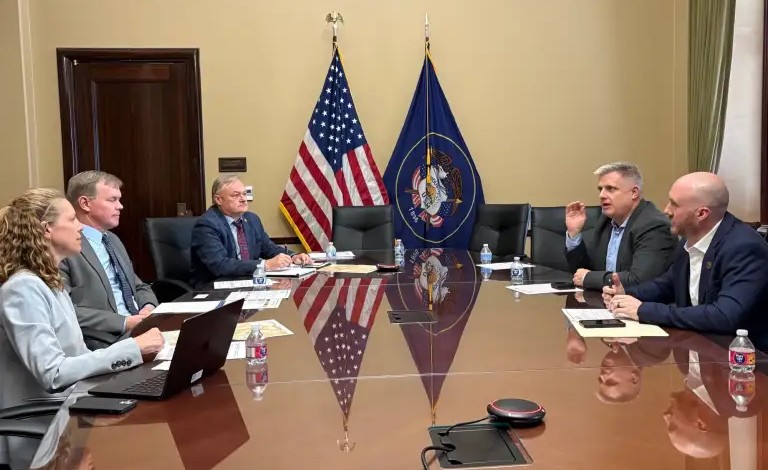 Chair Erik Rowland and Manager Dustin Grabeau, from Wasatch County, met with Waldrip and Mike Mower of Governor Cox’s office, to smooth out some misunderstandings. Park Record Report Salt Lake TRIB Report
Here’s Erik’s post on Facebook. Not much more has been said about the meeting:
Erik Rowland “Myself along with our county manager met today with representatives from the Governor’s office following a statement made last week threatening the county’s state funding could be affected by its position on certain state housing initiatives.
Wasatch County values its working relationship with the state and believes that relationship is necessary to get things done for our residents. At the same time, the county will not change its position on local decisions based on a threat, and today’s conversation did not change that.
 **INSIDE UTAH POLITICS interview on KTVX (go to 10:30 into recording) with Waldrip, in early October 2026, gets into it! Lindsay Aerts had to ask the same question 3 or 4 times to get Waldrip to admit THE Governor told him to threaten Wasatch County. Finally!
_______________________________________
Heber Valley Economic Development WEBSITE
Economic Development Annual Reports
Heber Chamber & Economic Development YOUTUBE page
2019- The Legislative Auditor has done an audit, of the TRT (transient room tax) money, of several counties – Davis, Garfield, Grand, Salt Lake, Wasatch, Washington, Wayne, and Weber. At the MAY 1, 2019 County Council Meeting, the County Manager will present a report to the council and public on these TRT monies.
TRT Revenue Growth for 29 Counties from Fiscal Year 2013 to 2017 is in the FULL audit. These numbers differ slightly from those in the bulk of the report because the Tax Commission operates on fiscal years, while counties operate on calendar years. Here is the increase in TRT $$$ for Wasatch alone:
County 2013 2014 2015 2016 2017 Total
Wasatch 1,270,597 1,401,805 1,423,479 1,548,326 1,864,285 7,508,491
TRT Revenue Percentage Growth Year-to-Year from Fiscal Year 2013 to 2017. (Each year’s percentage growth is calculated using the previous year as a baseline. The 2013 baseline is not shown as the percentage change between the first two years is represented in 2014.)
County 2014 2015 2016 2017 5-year growth
Wasatch 10% 2% 9% 20% 47%
KSL Article Gehrke- Salt Lake Trib Article
(From the audit) Usage Is Restricted – Counties can charge a tax of up to 4.25 percent on hotel or other accommodation stays. These taxes are charged by the hotels and then remitted to the Utah State Tax Commission. The Tax Commission then distributes these funds to the counties.
Utah Code Allows TRT Funds to Be Used for Four General Tourism-Related Purposes. These purposes will be discussed in more detail further in the report.
- Establishing and promoting recreation, tourism, film production, and conventions Promotion
- Acquiring or operating convention rooms, visitor information centers, museums, or sports and recreation facilities Acquiring and Operating
- Acquiring or making payments for land or infrastructure improvements for use 2 Payments
- Mitigation of tourism impacts for solid waste disposal, emergency medical services, search and rescue, law enforcement, and road repair for class B through D roads. This use is only allowed for 4th through 6th class counties Mitigation
In 2017 the Eight Sampled Counties Spent More Money Advertising Out-of-State Than in Utah. Staffing and operations includes counties’ tourism staff costs, buildings, visitor center costs, and some travel. The percentages in this figure are estimates based on the best data we could gather.
County Total Promotional Spending* In-State Out-of State Staff&Operations
Davis $1,076,000 29 % 38 % 33 %
Garfield 1,269,200 13 66 21
Grand 2,801,200 15 72 13
Salt Lake 10,031,900 0** 40 60
Wasatch 692,000 10 30 60
Washington 3,392,200 7 70 23
Wayne 321,000 10 51 39
Weber 880,000 3 39 58
(Source: Auditor Analysis of County Data
* The numbers in Figure 3.1 do not match those listed in Figure 2.2 because this figure shows only the promotion total and does not include any project spending.
** Salt Lake County reports that, because they try to advertise only to larger markets, their promotion dollars are all targeted outside the state)
Few Counties Submit Tourism Revenue Reports
In 2016, 16 of the 29 Utah counties submitted reports to the Governor’s Office of Economic Development (GOED) through the Utah Office of Tourism (UOT). 19 By the inception of the audit in July 2018, UOT had received 2017 reports from just 3 of the 29 counties.
Compliance rates were higher in 2016 than 2017. These numbers reflect tourism revenue reports received before the audit’s inception in July 2018.
County 2016 2017
Davis Yes No*
Garfield No No
Grand Yes No
Salt Lake No No
Wasatch Yes No
Washington Yes No*
Wayne Yes No
Weber Yes No*
Count 6/8 0/8
****MORE recent WASATCH CO. AUDITS——–
2019- Auditor- Internal Control Report Card
2018 Auditor report of Wasatch Co Internal controls 10-2018
Wasatch County Council Response- 2018 Audit Wasatch Co RESPONSE
RECOMMENDATIONS– 1. INADEQUATE SEPARATION OF DUTIES OVER CASH ACCOUNTS
By definition, all treasurers have access to entity bank accounts and cash receipts. Likewise,
accountants have access to financial records and systems. This inherent access to cash and record
keeping creates a risk of undetected theft or unauthorized disbursements. To manage the risk
associated with these key financial duties, the treasurer must perform certain tasks to check the
accountant’s control over record keeping and the accountant must perform certain tasks to check
the treasurer’s access to cash receipts and bank accounts.
In Utah, county treasurers collect property taxes for all local government entities within each
county. The property tax collection account (Treasurer’s Trust Account) is especially risky since
most property tax software does not integrate with the accounting system for the rest of the
county accounts. This lack of integration can create a scenario where the county treasurer
performs all of the accounting and treasurer duties for the Treasurer’s Trust Account.
Recommendation:
We recommend the County separate the duties of record keeping and reconciliation of both
the property tax collection account (Treasurer’s Trust Account) and the county operating
accounts. This should be accomplished by having a person outside of the treasurer’s office
directly receive the bank statements from the bank and perform the bank reconciliation of
the Treasurer’s Trust Account. Also, someone in the Treasurer’s office should directly
receive the bank statements from the bank and reconcile all county operating accounts
2. INADEQUATE GENERAL INTERNAL CONTROLS were cited by the auditor.
a. (Question 16) The County does not appear to provide management with monthly financial
reports comparing current year-to-date spending to the budget.
Recommendation:
We recommend the County provide management with monthly financial reports that
compare current year-to-date spending to the budget.
b. (Question 17) The County does not appear to prepare a monthly bank reconciliation of all
bank accounts.
Recommendation:
We recommend the County perform a monthly reconciliation of all bank accounts.
c. (Question 21) The County does not appear to perform detailed tracking of awarded cash and
gift cards, including award type (cash vs. gift card, noting retailer), recipient names, and
dates and amounts awarded.
Recommendation:
We recommend the County provide a detailed tracking awarded cash and gift cards,
including award type (cash vs. gift card, noting retailer), recipient names, and dates
and amounts awarded.
d. (Question 24) The County does not appear to have procedures in place to ensure that a nonsubordinate of the credit or purchase card holder reconciles original receipts to original
statements to ensure all transactions are appropriate, authorized, and supported by
documentation.
Recommendation:
We recommend the County implement procedures to ensure that a non-subordinate of the credit or purchase card holder reconciles original receipts to original statements to ensure all transactions are appropriate, authorized, and supported by documentation.
e. (Question 25) The County does not appear to have a process in place to ensure officers and
employees disclose conflicts of interest in accordance with Utah Code 17-16a.
Recommendation:
We recommend the County implement a policy that ensures officers or employees
disclose conflicts of interest in accordance with Utah Code 17-16a.
______________________________________
See what the future looks like! ONE WASATCH Ski link presentation- ONE Wasatch
See the NEW MOUNTAIN ACCORD redevelopment plan for the Wasatch Back here. Wasatch and Summit County entities are collaborating to ensure a vision in economic, transportation, and enviromental issues on the Wasatch Back.
Watch videos here! Wasatch Taxpayers YouTube page
_________________________________________
Wasatch County Economic & Tourism Board Budget 2010-2012
Wasatch_County_Council-December5th2012-Mtg-Notes-AWardell
Wasatch_County_Council-December5th2012-Mtg-Agenda
Wasatch County Transient Room Outlets (active accounts only)